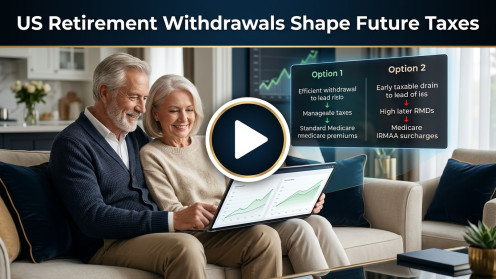
With over four decades guiding clients through Medicare and retirement planning, I’ve seen how withdrawal strategies can significantly impact your long-term tax picture and health coverage costs. Consider this: two retirees with identical $2.1M portfolios may end up with very different tax bills, all because of early withdrawal decisions and how their assets are allocated. If your portfolio is split between taxable accounts and a traditional IRA, your choice of which to tap first can shape your yearly income—like the $117.4K example—but, more importantly, it determines both your current tax efficiency and future liabilities. For joint filers in 2026, keeping your Modified Adjusted Gross Income (MAGI) at or below $218,000 means standard Medicare premiums. Go even one dollar over, and your Part B premium can jump by nearly $284, plus potential Part D surcharges. Draining taxable accounts first might let your IRA grow, but that can lead to larger required minimum distributions (RMDs) and higher tax pressure down the line. On the other hand, planned IRA withdrawals or conversions before RMD age can ease future burdens. Before the year wraps up, it’s wise to model your RMD path, keep any conversions under the next IRMAA threshold, and review IRA investments for risks like floating rates, leverage, or over-concentration. Thoughtful planning now can help protect both your wallet and your Medicare benefits.
Leave a Reply